




Horst Wickinghoff
Senior New Business Manager
- Company Formation
- Tax Structuring

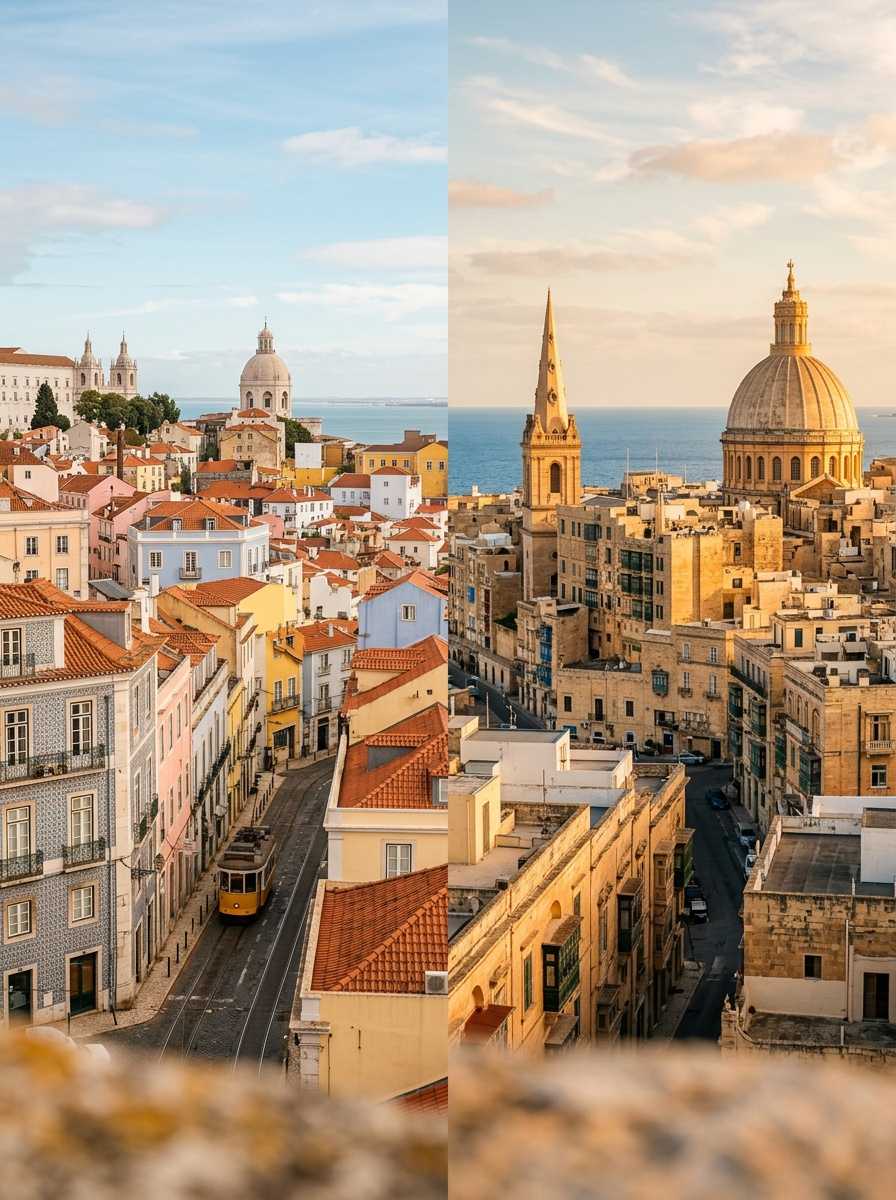
Jurisdiction Comparison
The NHR regime closed at the end of 2024. Its successor, IFICI, targets only specific professions. For UK and international entrepreneurs who previously considered Portugal, the landscape has fundamentally changed. We break down the new rules and compare them with Malta.
Independent Analysis · Based in Malta since 2013
Last updated: October 2026
For years, Portugal was an attractive destination for international taxpayers thanks to the NHR regime. Since late 2024, the NHR is closed, and its successor (IFICI) applies only to specific roles and professions. For UK entrepreneurs and freelancers seeking a broadly applicable tax programme, Portugal has lost much of its appeal. Malta offers a predictable alternative with its refund system (5% effective corporate tax), the Global Residence Programme (15% on foreign income remitted to Malta, open to UK nationals, no industry restrictions), and an active Double Tax Treaty with the UK. Both are EU members, but their tax frameworks differ significantly following the end of the NHR.
Direct Comparison
Portugal and Malta after the end of the NHR, compared on ten criteria, from corporate tax and special tax programmes to crypto, residency permits, language and authorities.
| Direct Comparison | Portugal | Malta |
|---|---|---|
| Corporate Tax | 19% standard rate since 2026 (2027: 18%, from 2028: 17%). With Municipal and State Surcharges, a marginal rate of up to 29.5% on very high profits. | 35% nominal. 5% effective rate via the EU-compliant refund system (6/7ths refund). |
| Special Tax Programme | IFICI (NHR successor): 20% flat tax on qualifying employment and self-employment income. Only for defined roles, e.g. in research, certified startups or highly qualified professions. Entrepreneurs only in specific cases, e.g. as board members of a certified startup. | Global Residence Programme (non-EU nationals, including UK citizens): 15% on foreign income remitted to Malta, minimum tax EUR 15,000/year (EUR 35,000 for applications made from 2027). No industry restrictions. |
| Personal Income Tax (PIT) | Progressive up to 48%, with the solidarity surcharge a marginal rate of up to 53%. Without a special programme, full taxation under regular Portuguese law applies. | Progressive up to 35%. Under the Global Residence Programme, foreign income remitted to Malta is taxed at 15%; Malta-source income at 35%. |
| Crypto Taxation | Capital gains from crypto are tax-free after a 365-day holding period. Shorter holding periods face a 28% flat tax. A genuine advantage for long-term crypto investors. | Long-term crypto gains for private individuals are generally tax-free. Commercial crypto trading is subject to regular corporate taxation. |
| EU Membership | Yes. Full single market access, freedom of services, EU regulatory framework. | Yes. Full single market access, freedom of services, EU regulatory framework. |
| DTT with the UK | Active Double Tax Treaty with the United Kingdom. | Active Double Tax Treaty with the United Kingdom (SI 1995/763). |
| Residency Permits | D7 visa (passive income), Golden Visa (funds only, from EUR 500,000; real estate route largely closed). EU citizens do not need a visa. | EU citizens: local registration. Non-EU nationals: Single Permit or Residency Programmes. Fast processing times. |
| Banking for UK Clients | Solid. EU-regulated banking system. Account opening is predictable but can be more time-consuming than in Malta. | Solid. EU-regulated, MFSA oversight. Account opening is predictable and well-established for international clients. |
| Cost of Living | Moderate to affordable. Lisbon is more expensive than the rest of Portugal. Overall, well below UK cost of living. | Moderate. Lower than London, comparable to southern European standards. Prime real estate is more expensive than rural Portugal. |
| Language / Authorities | Portuguese. Administrative processes are often in Portuguese; English is increasingly accepted but not universally. | Maltese and English. All official processes are in English. No language barrier. |
Since 2009, the Non-Habitual Resident (NHR) regime was Portugal's main draw. Foreign arrivals paid a flat 20% tax rate on certain Portuguese income for ten years, while many foreign income sources were completely exempt. For UK entrepreneurs, freelancers, and retirees, this was a highly compelling offer.
Add to this the high quality of life: Lisbon and the Algarve offered a mild climate, lower living costs than the UK, and a growing international community. Portugal was attractive not just for tax reasons, but as a place to live. Many UK expats put down roots there.
The business infrastructure also improved: coworking spaces in Lisbon and Porto, a growing startup ecosystem, and relatively straightforward residency options via the D7 visa or Golden Visa programme made relocating easy.
This all changed when the Portuguese government announced the end of the NHR regime in 2023, closing it permanently at the end of 2024. The final transition period expired in March 2025. What remains is no longer sufficient for most UK and international entrepreneurs.
The NHR regime was the tax backbone for many international arrivals in Portugal. The exemption of foreign income and the 20% rate on certain Portuguese income made the jurisdiction attractive even for entrepreneurs who did not meet specific industry requirements. With the end of the NHR, this foundation is gone. Anyone moving to Portugal now, without qualifying for IFICI, is subject to regular progressive income tax up to 48%.
The IFICI (Incentivo Fiscal à Investigação Científica e Inovação) is the successor to the NHR, but with a significantly narrower scope. It is tied to specific roles and types of entity, such as research, certified startups, companies recognised as relevant by AICEP or IAPMEI, and a list of highly qualified professions. The 20% flat tax remains, but the pool of eligible individuals has shrunk drastically. Independent entrepreneurs, consultants, e-commerce operators, or digital independents generally do not qualify, unless, for example, they serve as board members of a certified startup.
On the corporate side, the standard corporate tax rate has been 19% since 2026 (2027: 18%, from 2028: 17%). With the Municipal Surcharge and the tiered State Surcharge on the portion of profits above EUR 1.5 million, the marginal rate reaches up to 29.5%. This is significantly higher than Malta's effective 5% rate under the refund system. While Portugal offers a participation exemption for holding companies, this alone does not make it an attractive base for active trading companies.
One point often overlooked in comparisons: bureaucracy in Portugal remains challenging despite recent improvements. Administrative processes are predominantly in Portuguese, and waiting times for NIF numbers and residency permits can stretch to several months. Malta offers a practical advantage here with English-speaking authorities and predictable timeframes.
“Since the NHR regime ended, we have received a significant increase in enquiries from entrepreneurs who originally planned to move to Portugal. The disappointment is understandable. But an honest comparison shows that for most UK and international entrepreneur profiles, Malta was structurally the better choice even before the NHR closed.”
Dr. Jörg Werner
Founder, Dr. Werner & Partners
Portugal remains an attractive destination if tax planning is not your primary motive. Those choosing Portugal for its quality of life, climate, and culture - and who are prepared to pay regular Portuguese taxes - will find it an excellent place to live. It also remains appealing for long-term crypto investors thanks to the tax exemption after a 365-day holding period. Furthermore, qualified scientists or tech professionals who meet the IFICI criteria still benefit from the 20% rate.
Malta is the more stable choice for entrepreneurs seeking a predictable tax structure that does not depend on narrow professional qualifications. The refund system, offering an effective 5% corporate tax rate, is open to all industries. The Global Residence Programme, with its 15% rate on foreign income remitted to Malta, is not restricted to specific professions. Additionally, the active Double Tax Treaty with the UK provides legal certainty when relocating.
For UK entrepreneurs with ongoing business in the UK or across Europe, both jurisdictions offer EU access. However, Malta combines this EU access with a significantly lower effective corporate tax burden and broader access to special tax programmes for individuals. If you want to set up an active company and build genuine substance, Malta offers the better combination of tax efficiency, administrative ease, and English-speaking infrastructure.
Location Profile
Tax system, residency, practical assessment and key data - the complete profile of Portugal as a business location.
The IFICI came into force in 2024 as the successor to the NHR, continuing to offer a 20% flat tax on qualifying income in Portugal. The crucial difference: the target audience is radically restricted. The IFICI is tied to roles and types of entity rather than industries: research and science, certified startups, companies recognised as relevant by AICEP or IAPMEI, and a list of highly qualified professions. Entrepreneurs, freelancers, consultants, and digital independents are generally not eligible. Exceptions exist, for example, for board members of certified startups.
The framework conditions have also changed. The generous exemption for foreign income that made the NHR so attractive is much more limited under the IFICI. Those who do not fall into one of the defined professional categories are subject to the regular Portuguese tax system with rates up to 48%. For the vast majority of UK expats, the IFICI is therefore not an equivalent replacement.
By comparison: Malta's Global Residence Programme (GRP), which is open to UK nationals as non-EU citizens, offers a 15% flat rate on foreign income remitted to Malta, with a minimum tax of EUR 15,000 per year. For applications made from 2027, the minimum rises to EUR 35,000. Malta-source income is taxed at 35%. The programme is not tied to any specific profession. Anyone moving their tax residence to Malta who meets the criteria can use the programme, regardless of whether they are an entrepreneur, consultant, investor, or retiree.
We regularly advise clients who already live in Portugal or whose NHR status has expired, and who are now considering whether Malta is the better long-term option. Relocating from Portugal to Malta is relatively straightforward within the EU, but it requires careful tax planning.
Key questions include: When does your unlimited tax liability in Portugal end? Are there exit tax rules that apply upon departure? How will your corporate structure be transitioned? Under certain conditions, Portugal levies a tax on unrealised capital gains when you leave. The exact implications depend on your individual asset portfolio and length of stay.
The relocation process follows a clear pattern: analysing your tax position in Portugal, planning the Maltese structure (company formation, refund setup, residency permits), coordinating the move with tax support in both jurisdictions, and establishing ongoing compliance in Malta. In a free initial consultation, we can assess whether a move makes commercial sense for your situation.
Location vs. Malta
We analyse your business model, target markets, and current tax position in your home country. You receive a clear, actionable recommendation.
Together, we design the optimal corporate structure: holding company, trading entity, and refund setup, tailored to your specific situation.
We handle the entire incorporation process: Articles of Association, registration, tax enrolment, and bank account opening. Timeframe: 6-8 weeks.
Managing your move: residency permits, registration, national insurance, and finding accommodation. End-to-end support.
Bookkeeping, annual accounts, tax returns, and refund applications. We remain your dedicated point of contact for all tax and legal matters.
In a free initial consultation, we assess whether and how Malta works for you.
Senior New Business Manager

Tax Transformation Leader

Transparency matters to us. Here you will find answers to the most common questions on this topic.
No. The NHR regime was permanently closed at the end of 2024. The final transition period for applications initiated before the deadline expired in March 2025. Anyone moving to Portugal now falls under the regular tax system or must qualify for the much narrower IFICI programme.
The IFICI is tied to specific roles and entities: research staff, jobs and board positions in certified startups, roles in companies recognised as relevant by AICEP or IAPMEI, and a positive list of highly qualified professions. Only for that list does it require a doctorate or a degree plus three years of professional experience. Shareholders are excluded in that capacity. Independent entrepreneurs, consultants, and e-commerce operators generally do not qualify, except, for example, as board members of a certified startup. Approval is granted by the Portuguese authorities on a case-by-case basis.
That depends on your individual situation. If your NHR status has expired or you do not qualify for the IFICI, moving to Malta can offer significant tax advantages. Malta provides a 5% effective corporate tax rate via the refund system and a 15% rate on foreign income remitted to Malta under the Global Residence Programme, both without industry restrictions. We can evaluate your specific situation in a free initial consultation.
Both locations offer a Mediterranean climate, good infrastructure, and an international community. Portugal boasts a larger landmass, diverse nature, and a broad culinary scene. Malta offers shorter distances, English as an official language, and a compact, well-connected expat community. The choice here is personal, not tax-driven. If tax structuring is your main priority, Malta provides the better framework.
Our expertise is strictly focused on Malta. We do not advise on Portuguese tax law and do not set up companies in Portugal. However, we will assess your situation and give you an honest appraisal of whether Malta is the better option for your profile. If Portugal is objectively a better fit for you, we will tell you. The initial consultation is free and confidential.
Next step
In a free initial consultation, we will analyse your business model and determine whether Malta is the better choice for your situation. Honest, confidential, and with no sales pressure.

Roderick Galea
Managing Partner

Nathaniel Borg
Partner



and the team in Malta

Corporate Services at DW&P Dr. Werner & Partners are provided by DW&P Services Ltd. (C 103208) which is regulated by the MFSA and is licensed under Authorised Person ID: DSER-23577 to carry out the activities of a Class C CSP in terms of the Company Services Providers Act (Cap. 529 of the Laws of Malta).


